
| Q3 • 2026 |
TMGMultifamily
MARKET PULSE
A Snapshot of the Pacific Northwest Multifamily Housing Market
The third quarter of 2026 brought clearer signs of stabilization across the multifamily markets we track, although rent growth remains limited and competition continues to influence leasing strategy. Demand strengthened in several markets, helping absorb recently delivered inventory and reduce vacancy, while new construction has slowed in Portland, Vancouver and Salem. The Tri-Cities remains the primary exception, with
a comparatively large development pipeline.
Concessions remain common in certain segments of the market, particularly at properties in initial lease-up, those asking above-market rents, and communities located in highly competitive submarkets. These conditions continue to place pressure on effective rents as property owners and managers use incentives to attract and retain residents. This underscores the importance of competitive pricing, targeted concessions, and proactive retention strategies.
The Vancouver market continues to perform relatively well. Vacancy declined to 6.0%, down about one percentage point over the past year, while 1,015 units were absorbed compared with 668 units delivered. Asking rent growth is flat at 0.0%, with average asking rents around $1,725 per month. Continued population growth, in-migration and a slowing construction pipeline should support further stabilization.
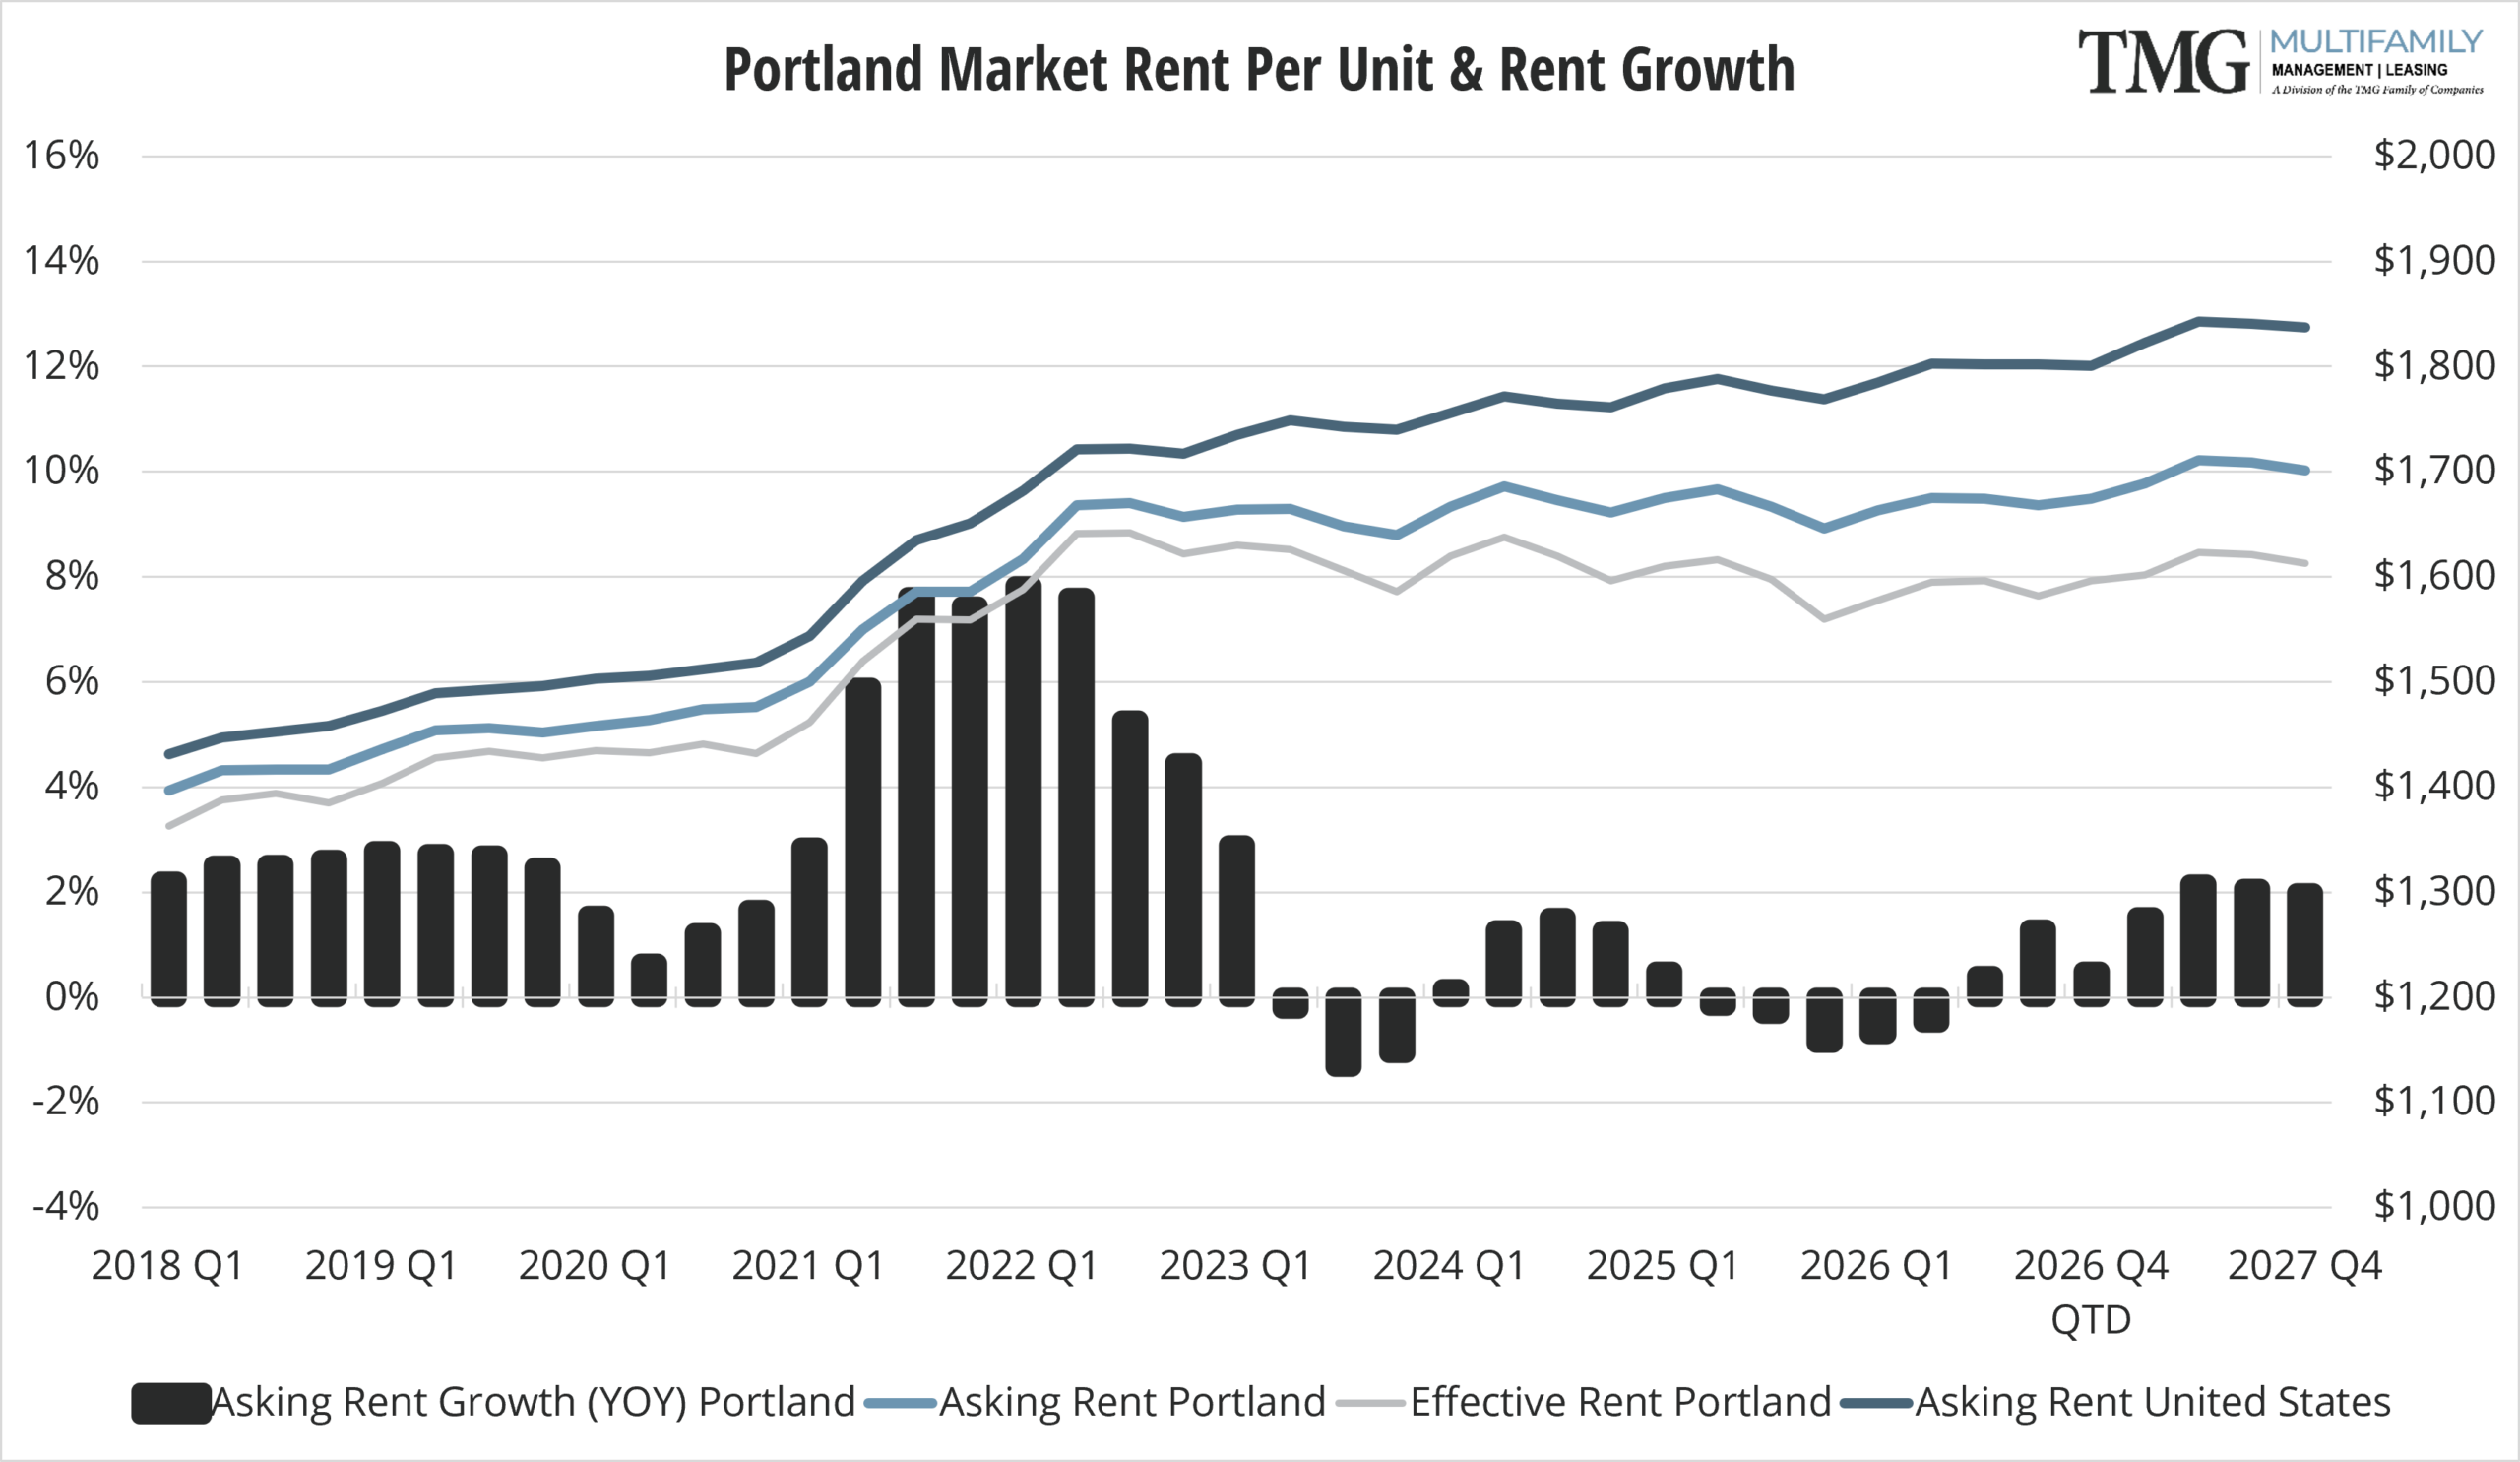
The Portland market is also showing improvement as its recent supply imbalance begins to ease. Vacancy has declined to 6.6%, compared with a 2024 peak of 8.0%, while trailing 12-month absorption reached 4,168 units versus 2,312 deliveries. Asking rent growth is slightly positive at approximately 0.5%, with average rents near
$1,674 per month. Class A properties remain the most competitive segment, with vacancy around 7.7% and sizable concessions still available in some urban submarkets.
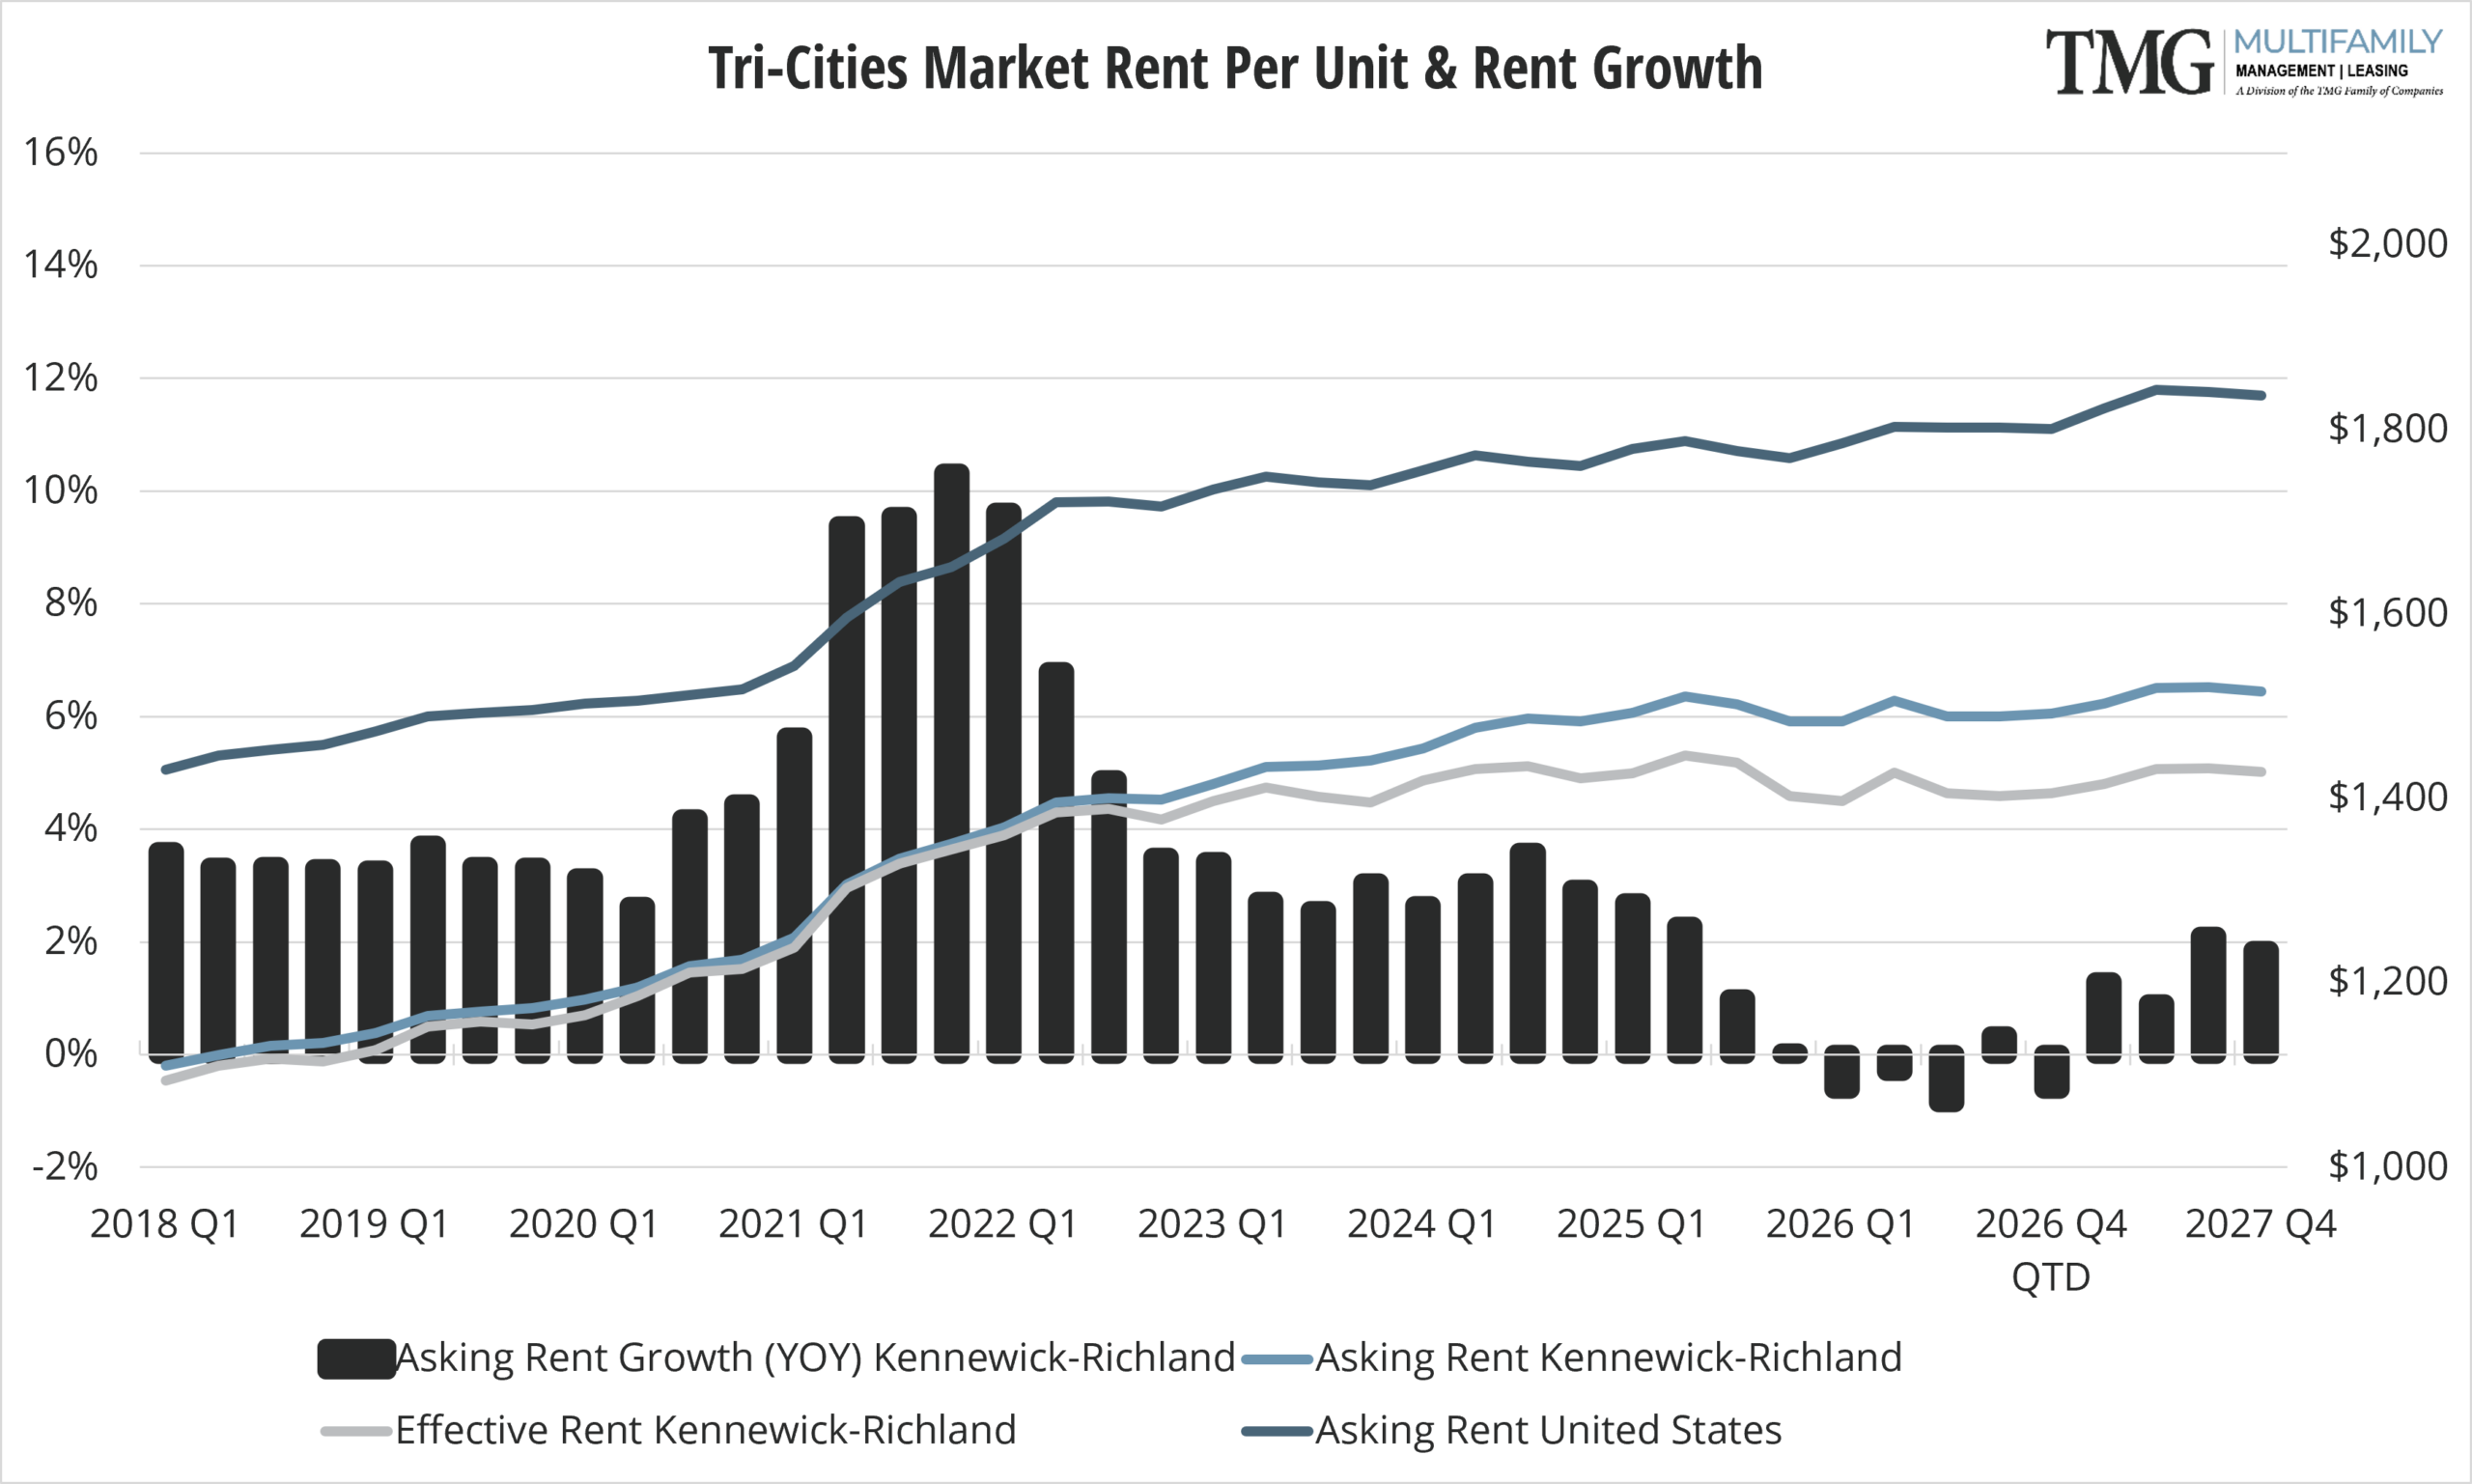
The Tri-Cities market posted the strongest vacancy improvement. Vacancy declined to 5.9%, down roughly three percentage points over the past year, as 740 units were absorbed compared with only 277 delivered. Average asking rent is approximately $1,490 per month, with annual rent growth at -0.6%. However, 925 units remain under construction, equal to about 5.8% of existing inventory, which could create renewed
competition as projects deliver.
Salem is still working through a recent supply surge. Vacancy stands at 6.7%, with 703 units absorbed compared with 1,049 delivered over the past year. Asking rent growth is -0.4%, and average asking rent is about $1,421 per month. The positive news is that construction has slowed sharply, with only 215 units currently underway, which should allow the market to gradually absorb excess inventory.
Across all four markets, the gap between asking and effective rents continues to show the impact of concessions. Renters remain price-conscious, and properties that push rents too aggressively may experience slower traffic, weaker conversion, and greater renewal resistance. Newer Class A communities remain especially exposed in Portland and Salem, while more established mid-tier and value-oriented properties generally face less direct competition.
The construction environment is also shifting. Portland has about 2,400 units under construction, down dramatically from nearly 12,900 units at the 2022 peak. Vancouver has approximately 1,166 units underway, while Salem has only 215. The Tri-Cities remains the outlier with 925 units under construction. This slowdown in most markets should help supply and demand move closer to balance through 2027.
Predictions for the remainder of 2026
The outlook across the four markets points toward gradual stabilization rather than a rapid rebound.
In Portland, demand is expected to continue outpacing deliveries, allowing vacancy to move lower while rent growth remains modest. Vancouver should continue to benefit from strong renter demand, slowing construction and gradual vacancy compression. Salem is expected to improve as its development pipeline shrinks, with vacancy forecast to move toward approximately 6.4% by year-end. In the Tri-Cities, strong
demand should continue, but new deliveries may temporarily increase availability; the report forecasts year end vacancy around 7.1% and rent growth of approximately 0.3%.
Bottom Line: The market is healthier than it was a year ago, but recovery remains uneven. Rent growth is likely to stay modest, concessions will continue to influence leasing decisions, and new supply will remain an important factor in select markets. Owners and operators who maintain realistic pricing, protect retention, monitor effective rents and respond quickly to changes in traffic and availability will be best positioned as conditions gradually improve.
VANCOUVERMultifamily
| 12 Mo. Delivered Units 668 |
12 Mo. Absorption Units 1,015 |
Vacancy Rate 6.0% |
12 Mo. Asking Rent Growth 0% |
Vancouver appears to be moving out of its high-supply-growth phase and into a more balanced market—flat rents today, improving occupancy, and signifcantly less new supply coming online.


PORTLANDMultifamily
| 12 Mo. Delivered Units 2,312 |
12 Mo. Absorption Units 4,168 |
Vacancy Rate 6.6% |
12 Mo. Asking Rent Growth 0.5% |
Portland’s market is gradually stabilizing, with vacancy declining, demand outpacing new supply, and rent growth expected to improve as construction remains limited.

SALEMMultifamily
| 12 Mo. Delivered Units 1,049 |
12 Mo. Absorption Units 703 |
Vacancy Rate 6.7% |
12 Mo. Asking Rent Growth -0.4% |
Salem's market is working through a recent supply surge, with soft rent growth and elevated vacancy today, but a much lighter construction pipeline should help conditions gradually stabilize.


TRI-CITIESMultifamily
| 12 Mo. Delivered Units 227 |
12 Mo. Absorption Units 740 |
Vacancy Rate 5.9% |
12 Mo. Asking Rent Growth -0.6% |
The market in Tri-Cities is showing strong demand and improving occupancy despite soft rent growth, although a sizable construction pipeline could create some near-term supply pressure.

Welcome to TMG Multifamily!
We are thrilled to welcome the following properties, which joined the TMG Family in Q3 2026:

Meadow Crest — 128 Units
Vancouver, WA
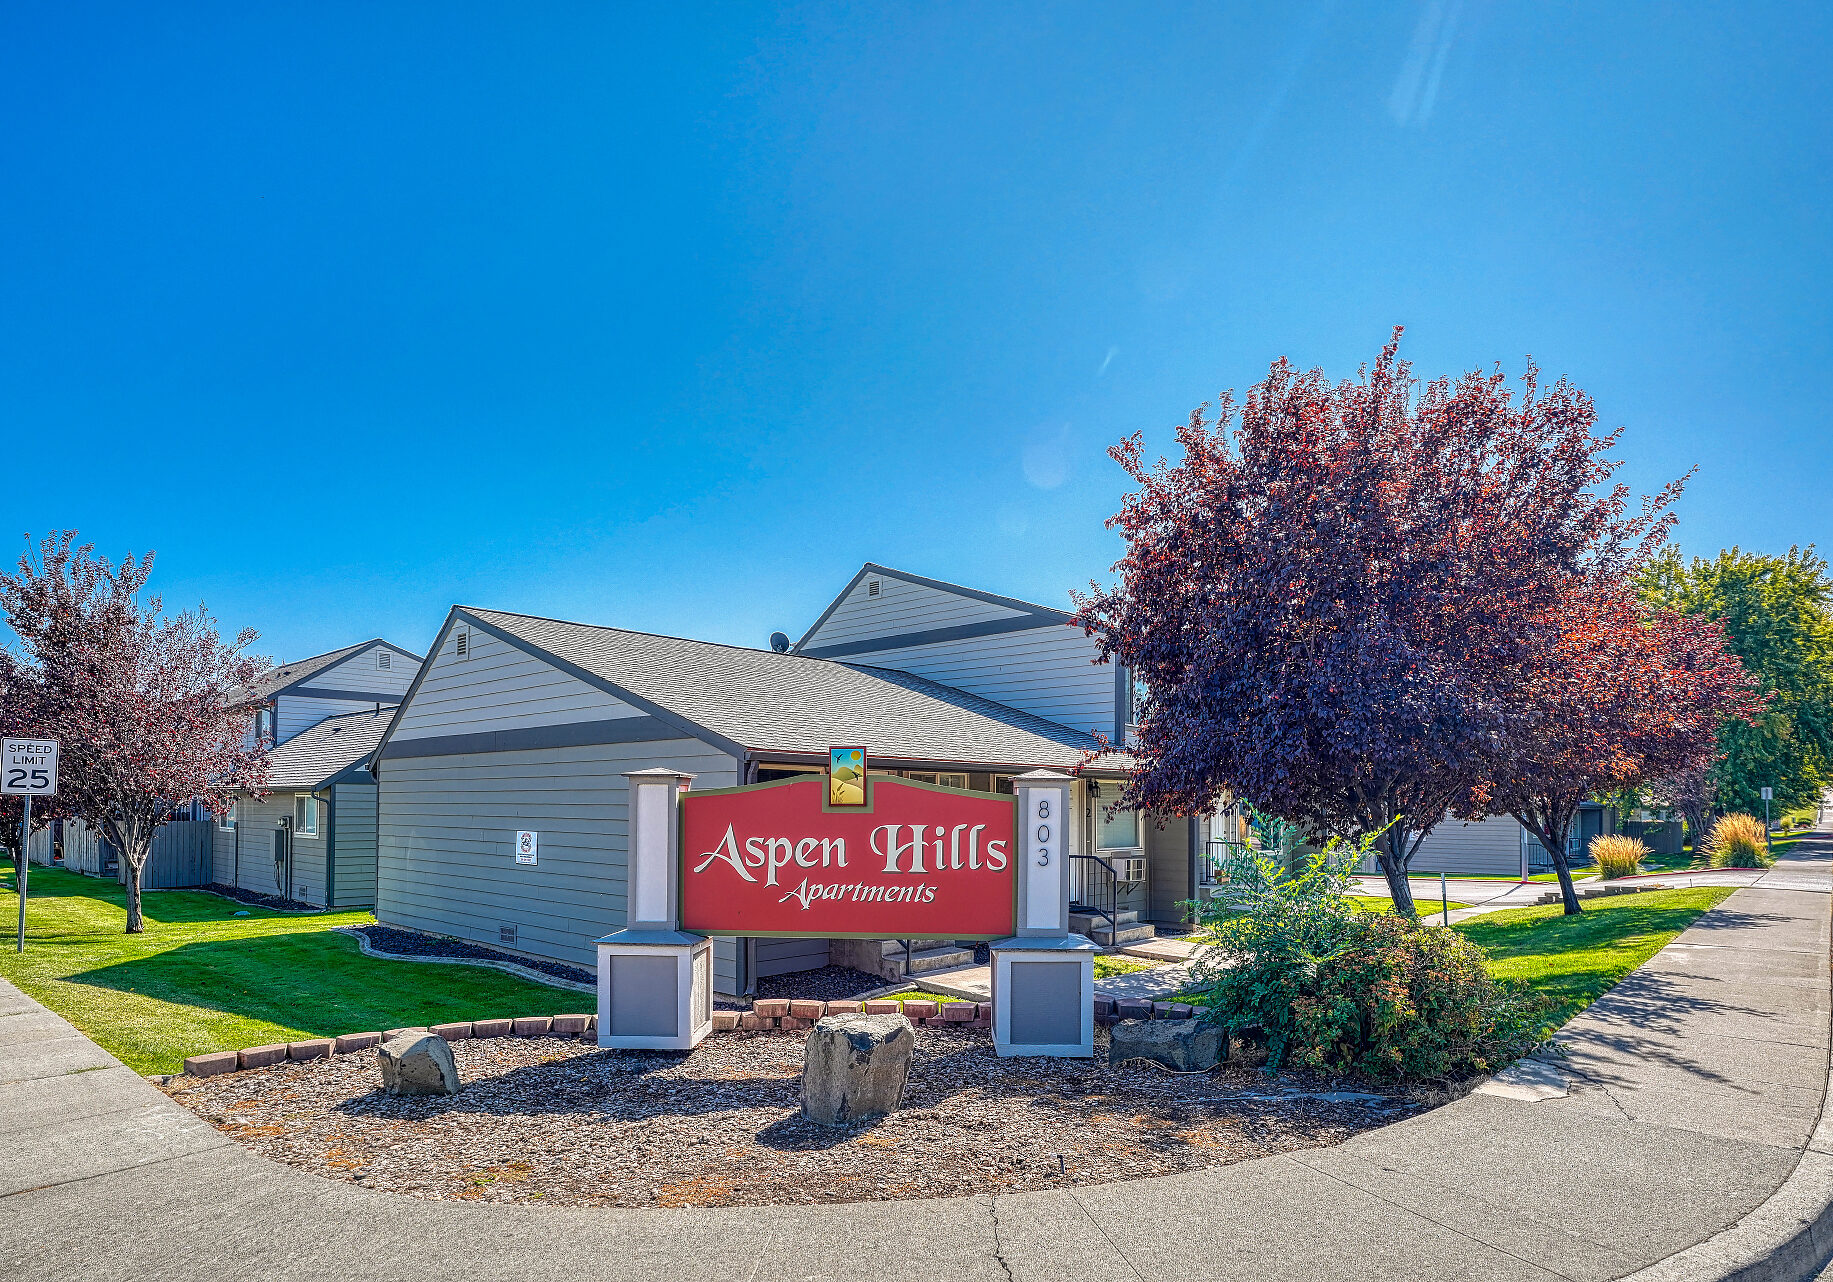
Aspen Hills — 136 Units
Kennewick, WA
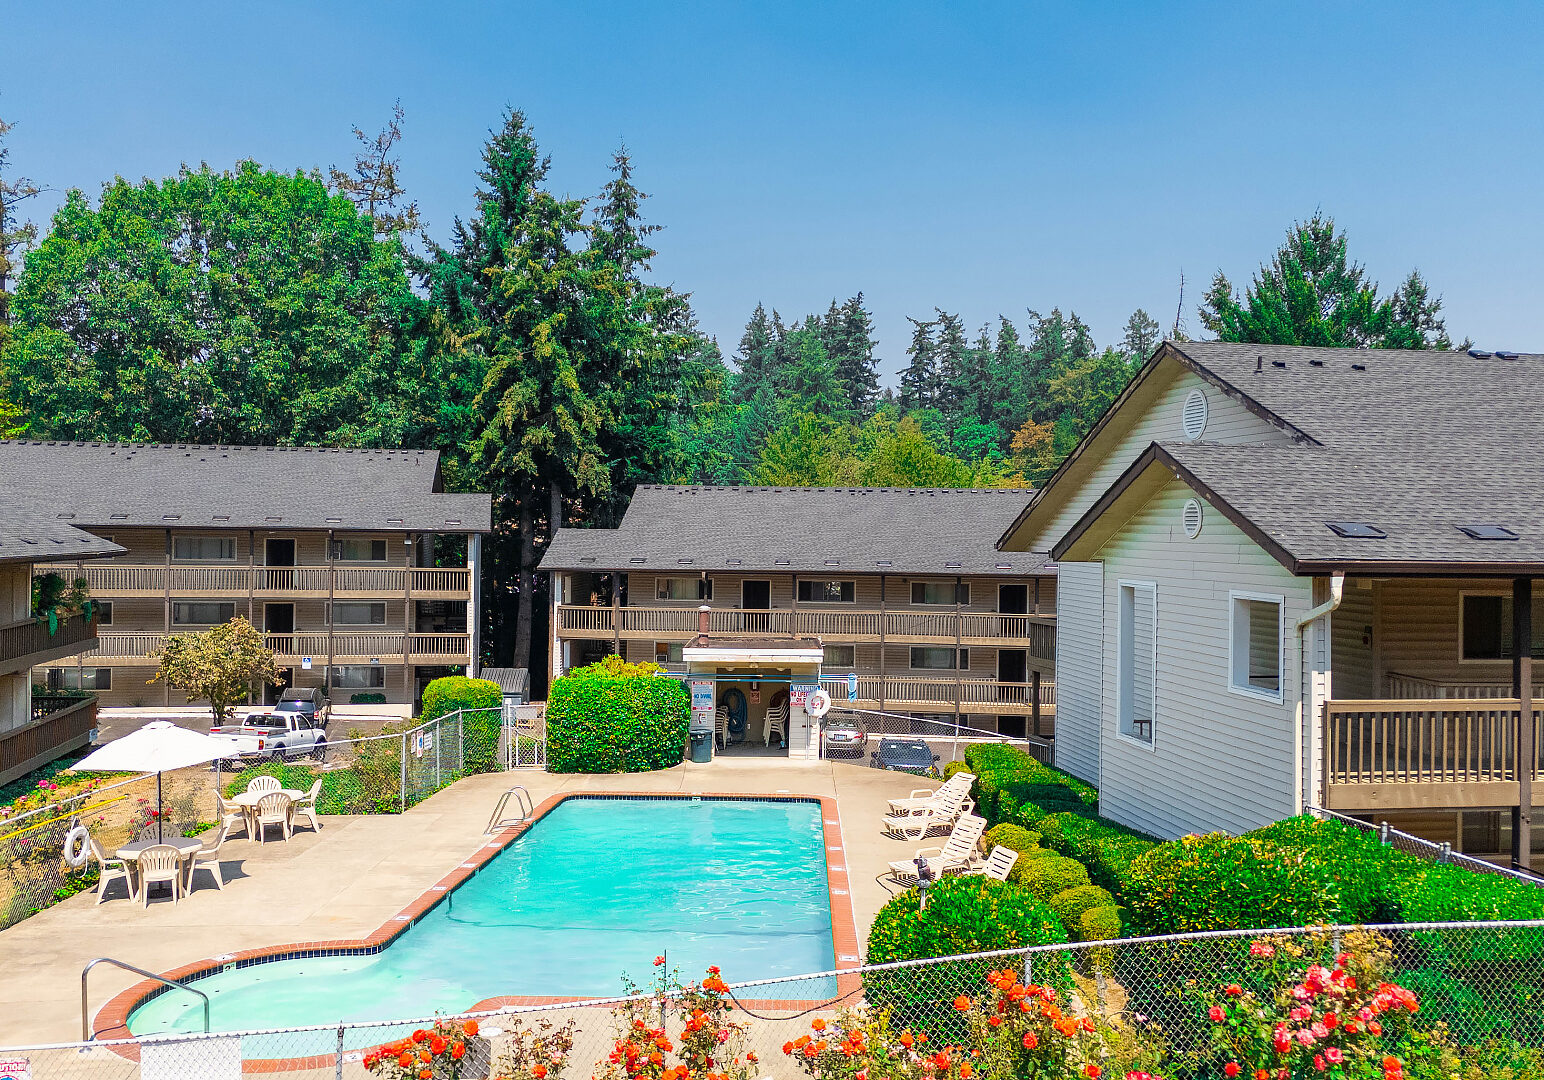
The Maples — 82 Units
Portland, OR
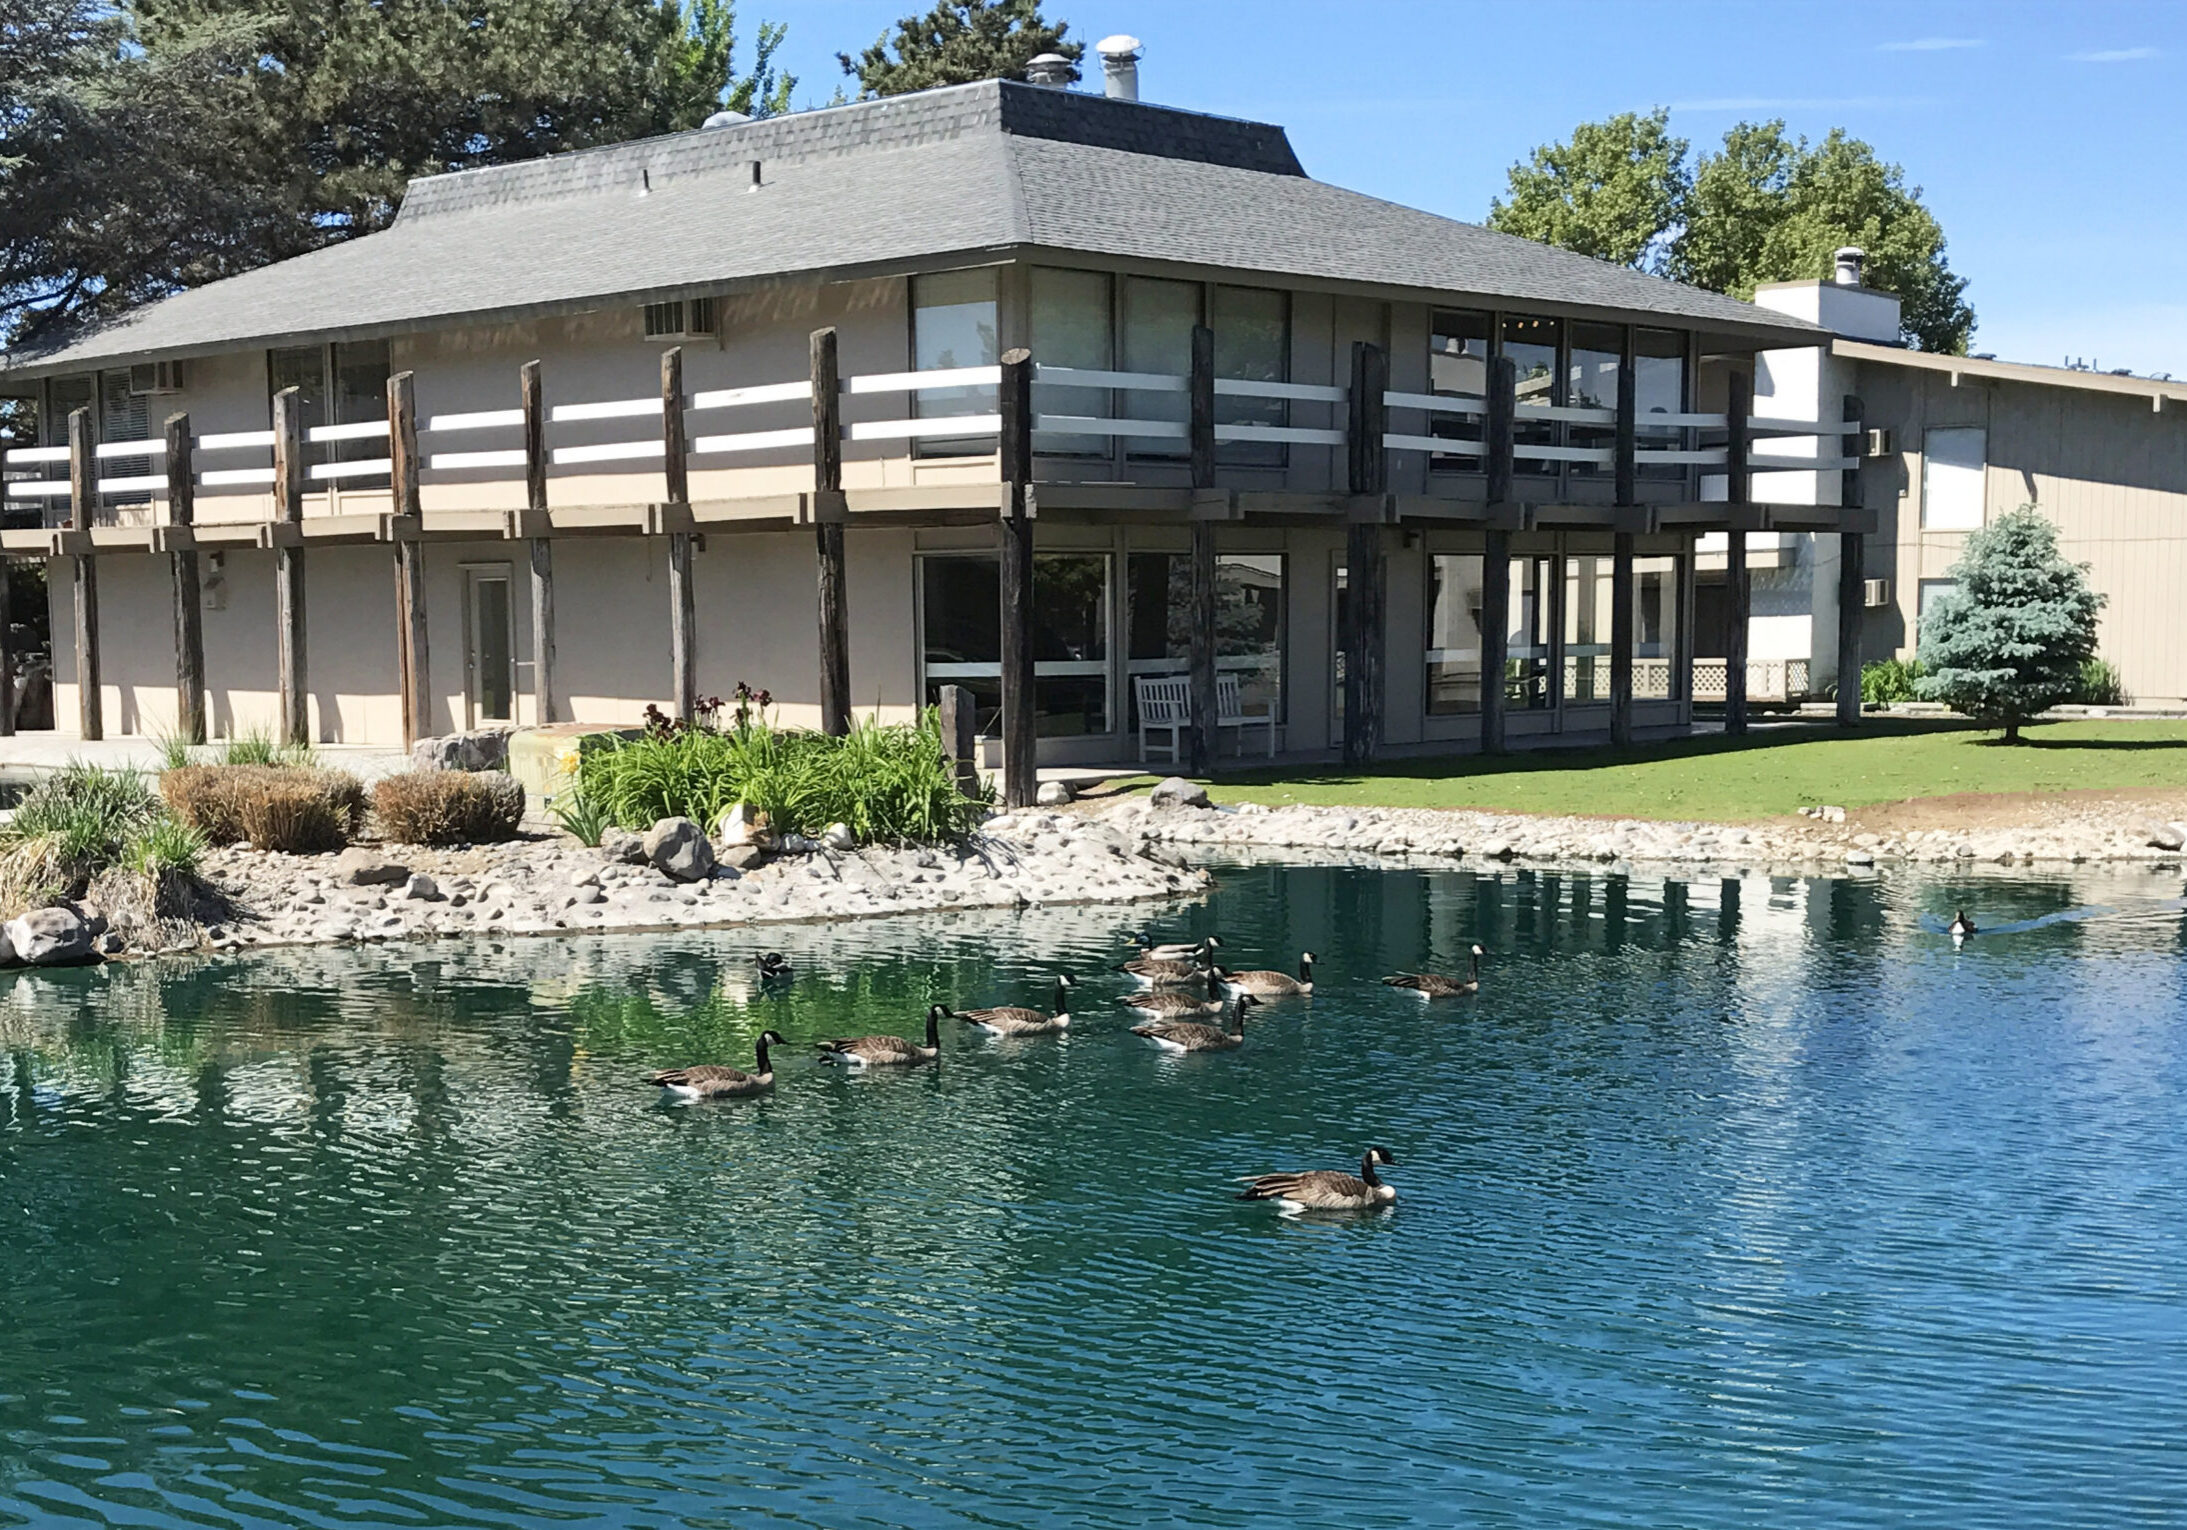
Lakeside Apartments — 121 Units
Kennewick, WA

Mountain View — 100 Units
Oregon, City, OR
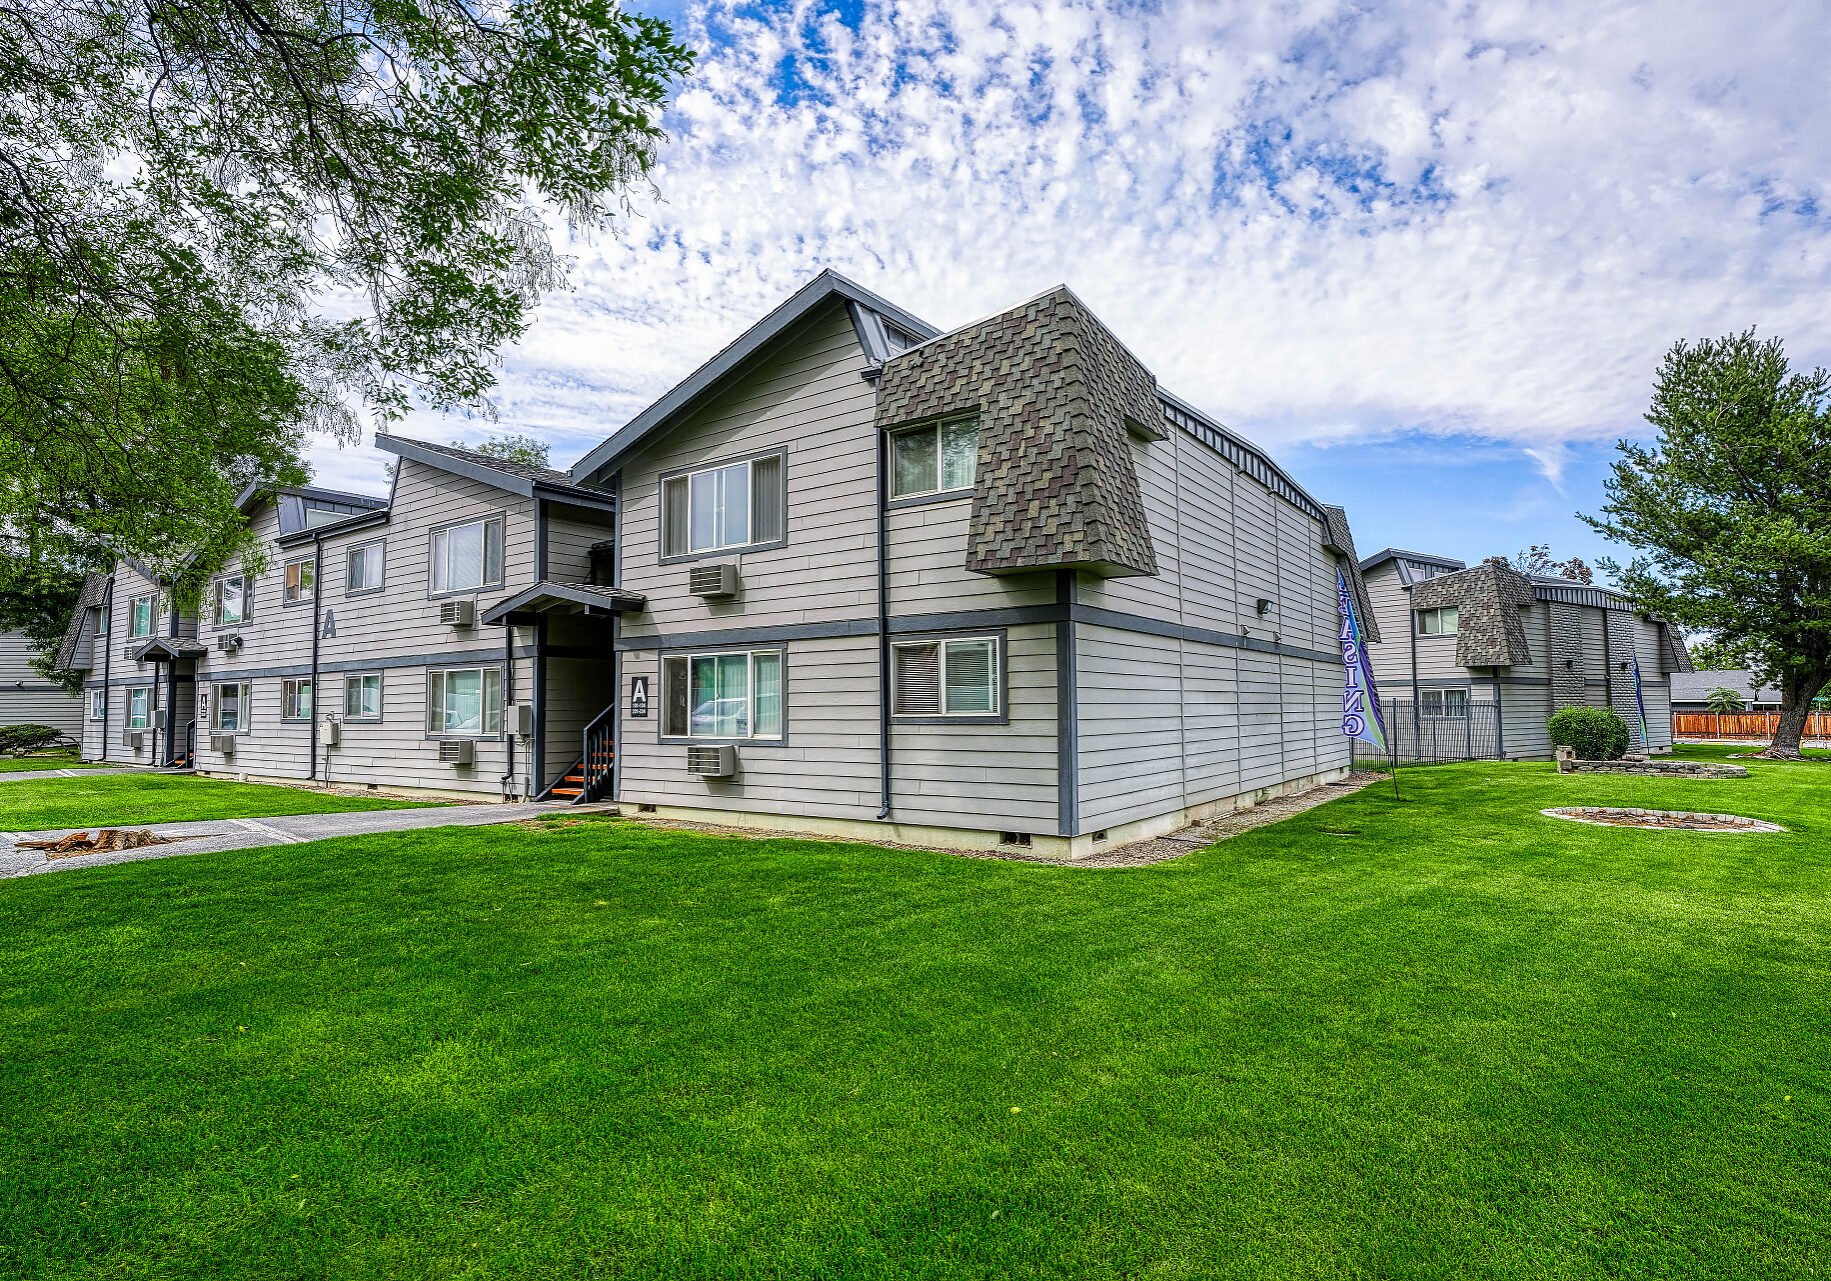
Crown Village — 89 Units
Kennewick, WA

Hidden Meadows — 82 Units
Kennewick, WA
Do you need management services?
Read about how TMG has helped investors like you achieve maximum ROI.
The TMG Multifamily Quarterly Market Pulse is brought to you by TMG Multifamily, an AMO accredited property management company providing a full suite of management services for existing apartments, new developments, lease-ups, and mixed-use properties. TMG partners with investors to proactively identify strategic opportunities and maximize their return on investment. Locally owned and regionally focused, TMG has been helping clients reach their financial goals since 1985.
CARMEN VILLARMA, CPM
President
The Management Group, Inc.
carmen.villarma@tmgnorthwest.com
(360) 606-8201
Vancouver/Clark County
7710 NE Vancouver Mall Dr Ste B
Vancouver WA 98662
Portland Metro
16520 SW Upper Boones Ferry Rd Ste 250
Portland OR 97224
Salem
698 12th St SE Ste 240
Salem OR 97301
Tri-Cities
30 S Louisiana St Ste 1
Kennewick WA 99336
All data in this report is pulled from CoStar.